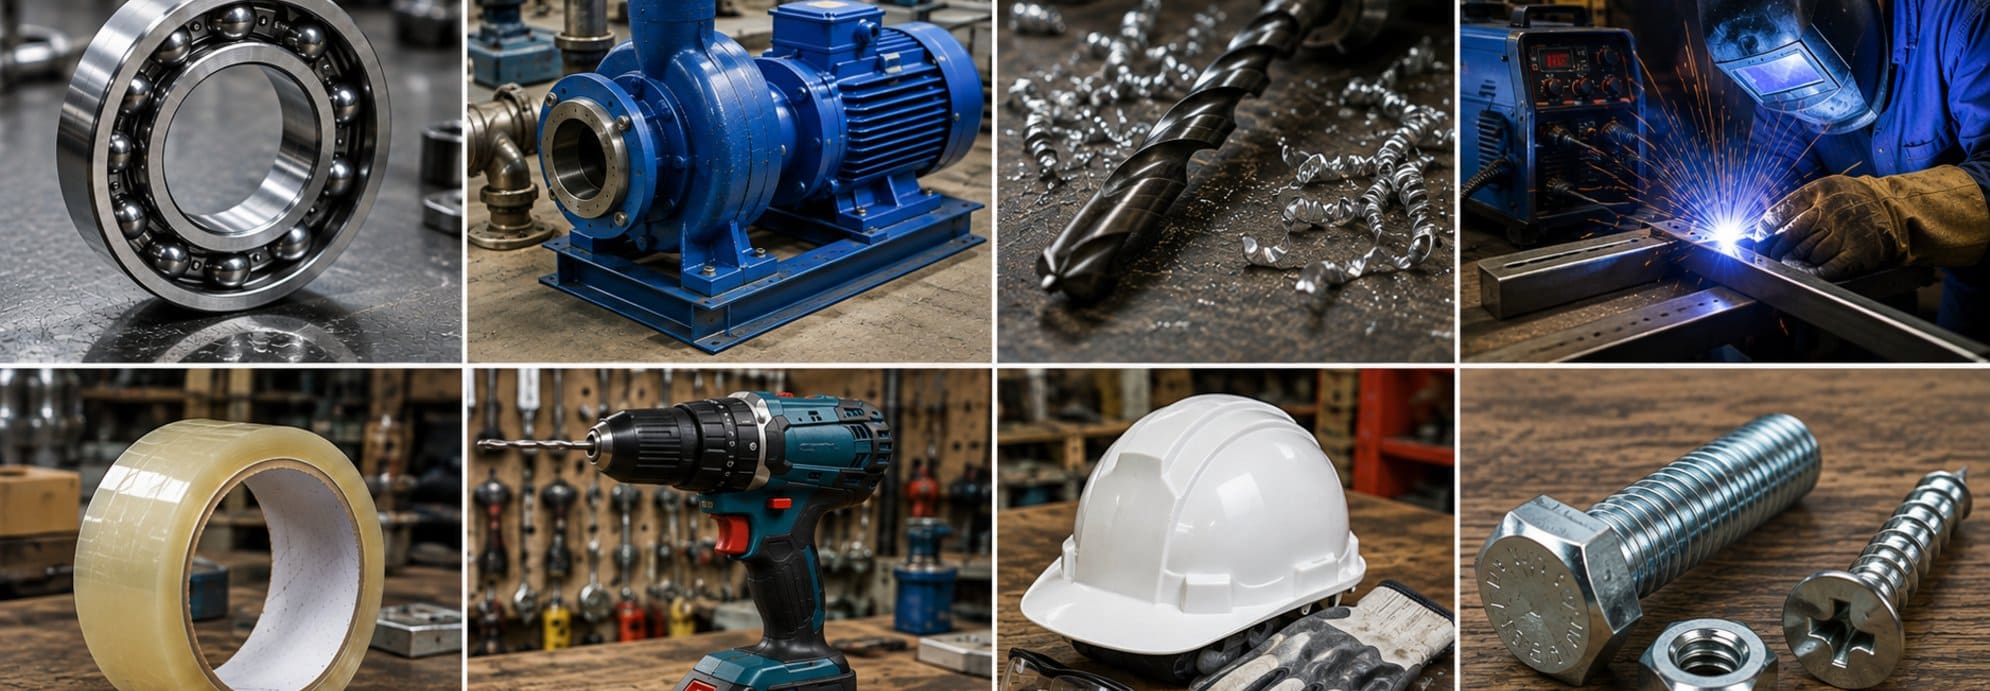
A market correlated with industrial GDP, still under-digitalized, and structured around eight families of products.
A €230bn market in Europe
- A European industrial supplies market of approximately €230 billion, of which distribution represents 50%
- Market breakdown:

- A market strongly correlated with industrial GDP trends
- Annual organic growth of around 2% per year (excluding exceptional periods)
- No major growth differences between European countries
- Sales digitalization that remains low
- 20% to 25% maximum for the largest players
- 5% to 10% for small and mid-sized players
A highly fragmented market, undergoing consolidation by major sector players and investment funds
Growing value-added services
A growth driver
- Advisory / recommendations
- Preventive / predictive maintenance
- Repair
- Product customization / assembly of systems or subsystems
- Multi-year service contracts
- Use of sensors to collect and monetize data
- Emergence of new services: heat recovery, product recycling / circular economy
A three-link value chain
Industrial manufacturers, large distributors, small distributors and resellers
Industrial manufacturers
- Industrial manufacturers serve major global or pan-European accounts directly, bypassing distribution
- They “delegate” distribution to small, medium and large accounts
- A trend toward reducing direct sales in favor of large distributors, as end customers prefer to consolidate their purchasing
Large distributors
- Large distributors sell mainly to end customers (80% of sales)
- They sell opportunistically to small distributors (20% of sales)
- Given the breadth of their product portfolio, large distributors are becoming go-to suppliers for small distributors and end customers
Small distributors and resellers
- They mainly serve local accounts and maintain strong personal relationships with their customers
- They have limited logistics and storage capacity, but provide high-quality, customized services
- They see large distributors as essential partners due to their wide range and product availability
« Source: Auteuil M&A Conseil »